Imagine navigating the world of insurance with ease, finding the best deals and understanding exactly what you’re paying for. Sounds like a dream, right? Well, if you’re in North Carolina, this dream could be a reality. In this comprehensive guide, we’ll unravel the complexities of insurance rates in NC, offering you insider information to secure the best rates and coverage.
From understanding what influences your premiums to comparing top providers, this guide is your one-stop destination for mastering insurance in the Tar Heel State. Let’s dive in and discover how you can make informed decisions that not only protect you but also save you money.
Understanding Insurance Rates in North Carolina
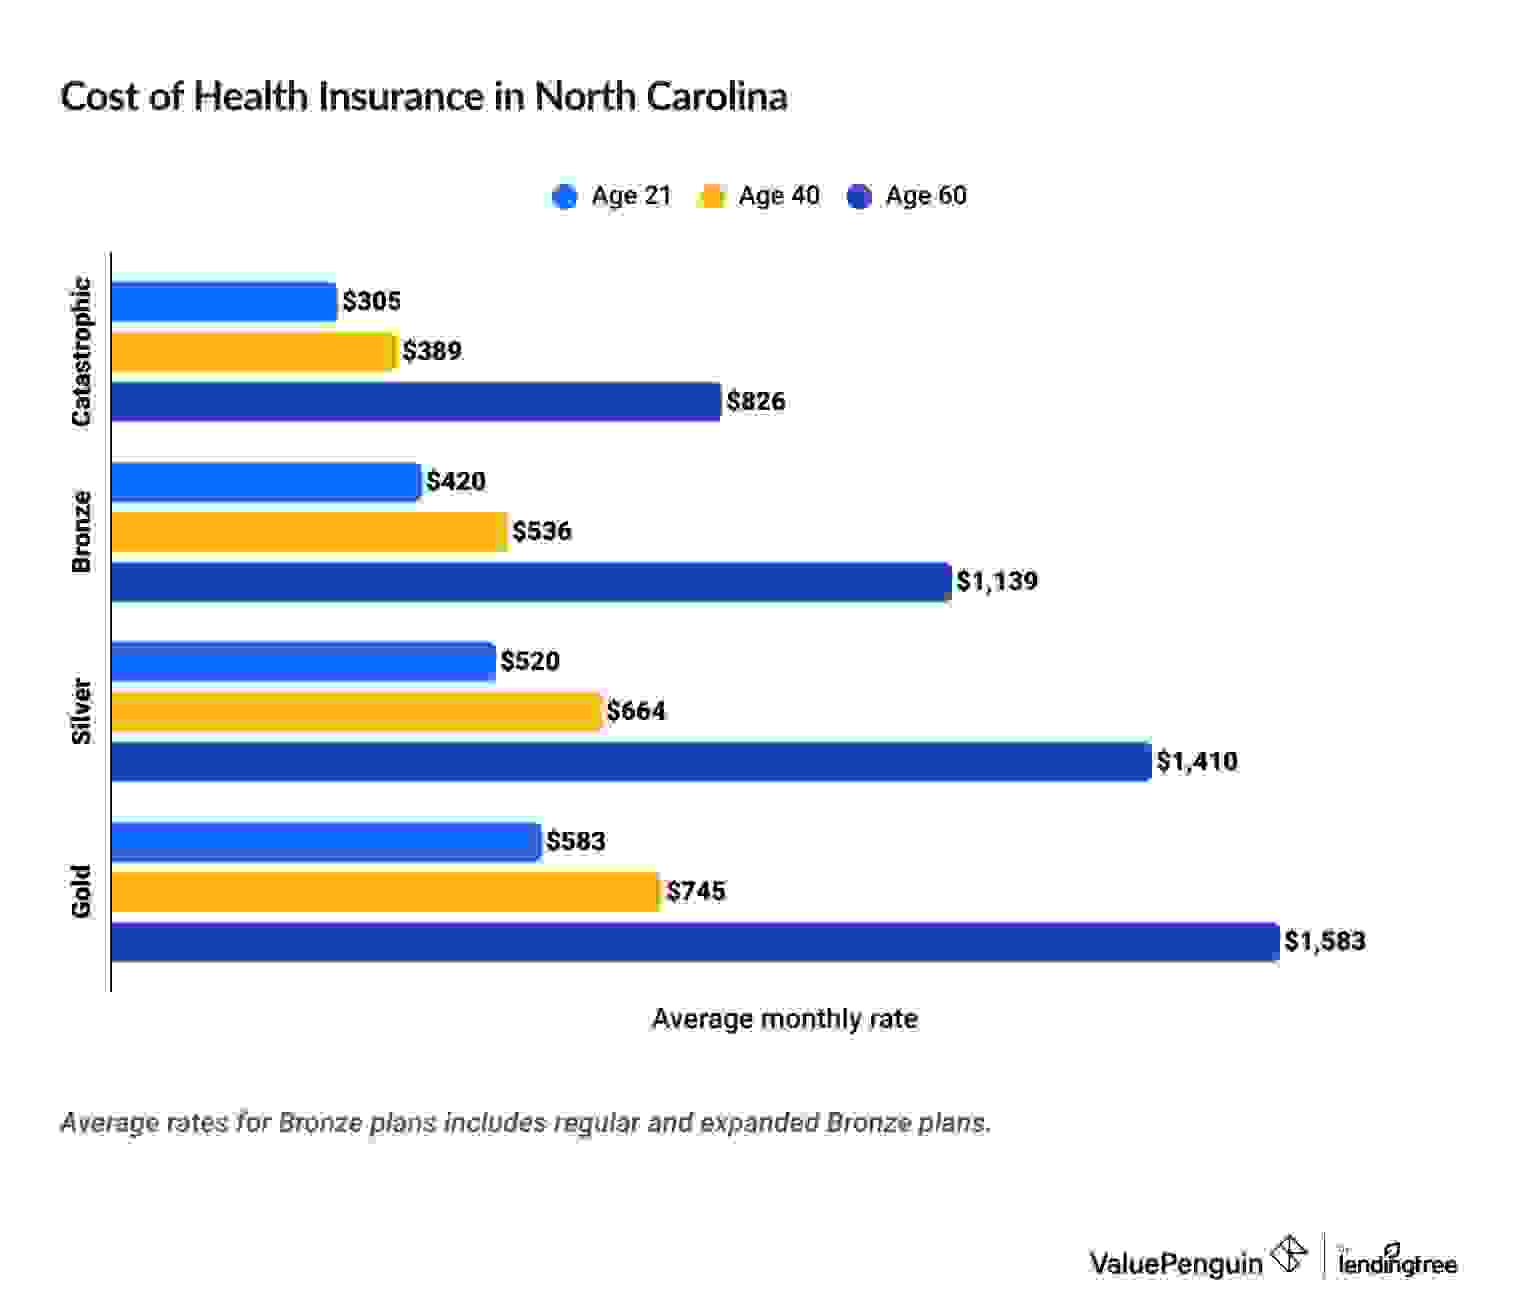
How much are you really paying for insurance in North Carolina? Many people don’t realize that rates can vary significantly, even within the same state!
Insurance rates in NC aren’t just pulled out of thin air. They’re a complex calculation that considers a host of factors, all geared towards assessing how much of a risk you pose to the insurer. Let’s dive into what that means for you.
Factors Determining Insurance Premiums
Insurance companies in North Carolina use several factors to determine your premium. Your driving record, the make and model of your vehicle, and even your credit score can all play a part. But here’s the deal: not all factors carry the same weight.
For instance, your driving record has a huge impact. A single speeding ticket can send your rates sky-high. And don’t forget your location! If you live in an area with high accident rates, expect to pay more.
Pro Tip: Regularly check your credit report. A better score could mean lower rates.
State-Specific Regulations Impacting Rates
North Carolina isn’t like every other state when it comes to insurance. There are specific regulations in place that aim to protect consumers from being overcharged. For example, NC has a unique system called the Rate Bureau, which sets minimum rates that insurers must follow.
But here’s the catch: these minimum rates can sometimes mean you’re paying more than if you lived elsewhere. It’s a double-edged sword designed to stabilize the market while ensuring fair prices for everyone.
The Role of Risk Assessment in Setting Rates
Risk assessment is the backbone of determining insurance rates. Insurers use complex algorithms to evaluate how likely you are to file a claim. This is where your vehicle’s safety features, your age, and even your commute distance come into play.
But remember, each insurer weighs these factors differently. That’s why shopping around can sometimes lead to significant savings. You never know which company might view you as a lower risk than others.
Pro Tip: Bundle your insurance policies to potentially save some serious cash.
Types of Insurance Available in NC
Did you know that choosing the right insurance can save you hundreds of dollars every year? North Carolina offers a variety of insurance policies tailored to meet your specific needs.
From auto to home, and even specialized insurance, the range of options seems endless. But understanding these options can make all the difference in finding the best coverage at an affordable rate.
Main Types of Insurance Policies in NC
In North Carolina, you’ll find all the standard insurance policies like auto, home, health, and life insurance. But here’s the deal: each of these has its own set of unique coverages. Let’s break them down.
- Auto Insurance
- Homeowners Insurance
- Health Insurance
- Life Insurance
- Renters Insurance
- Business Insurance
Whether you’re a new car owner or a seasoned homeowner, knowing the specific types of coverage within these policies is crucial.
Liability, Collision, and Comprehensive Coverage
When it comes to auto insurance, North Carolina drivers have three main types of coverage to consider: liability, collision, and comprehensive. Each serves a different purpose.
| Type | Description |
|---|---|
| Liability | Covers damages to others in an accident you cause. |
| Collision | Covers damage to your own vehicle from an accident. |
| Comprehensive | Covers theft and damage from non-collision events. |
Liability is typically required, but collision and comprehensive are optional. Choosing the right mix can save you money and provide peace of mind.
Examples of Specialized Insurance in NC
Beyond the standard policies, North Carolina offers specialized insurance options to cover unique needs. Here are a few examples:
- Flood Insurance
- Boat Insurance
- Motorcycle Insurance
- Pet Insurance
Pro Tip: If you live in a flood-prone area,
investing in flood insurance can be a lifesaver
. It’s often not covered under standard homeowners’ policies.
Benefits of Bundling Multiple Policies
One of the smartest moves you can make is bundling multiple policies with the same provider. Why? Discounts, convenience, and easier management.
Insurance companies love it when you buy more than one policy from them. And they reward you with significant discounts. But the benefits don’t stop there. Managing your insurance is simpler and more streamlined when it’s all under one roof.
By bundling, you can save money and reduce the hassle of juggling multiple policies across different companies.
Think of it as a win-win situation for both you and your insurer.
Comparing Insurance Providers in NC
Ever wondered which insurance provider in North Carolina gives you the best bang for your buck? Choosing the right insurer can be tough, but it doesn’t have to be.
Let’s break down the top contenders, so you can make an informed decision. We’re diving into customer service, claims processes, financial stability, and those all-important discounts!
Insurance Provider Comparison Table
Here is the deal: not all insurers are created equal. To make your life easier, I’ve put together a table that compares the top insurance providers in NC across four key areas.
| Insurance Provider | Customer Service Rating | Claims Process | Discounts Offered |
|---|---|---|---|
| State Farm | 4.5/5 | Streamlined and fast | Multi-policy, Safe Driver |
| Geico | 4.3/5 | Efficient online tools | Military, Good Student |
| Nationwide | 4.1/5 | Quick and responsive | Bundling, Anti-theft device |
| Progressive | 4.0/5 | User-friendly app | Continuous coverage, Homeowner |
Understanding Customer Service and Claims Process
Choosing an insurer isn’t just about the price. It’s about how they treat you when you need them the most. State Farm, for instance, excels in customer service with a 4.5 out of 5 rating.
But what about the claims process? Geico stands out with its efficient online tools that make filing a claim a breeze. You want an insurer that’s there for you when things go sideways, not just when they want your business.
Financial Stability of Major Companies
Insurance is about trust, and trust is built on financial stability. Here’s the kicker: you need a company that can actually pay out claims when disaster strikes.
Pro Tip: Always check the financial stability ratings of your insurer. A company like Nationwide with high ratings from agencies like A.M. Best is a safer bet.
Discounts Offered by Leading Insurers
Everyone loves a good deal, right? Here’s a little secret: discounts can make a huge difference in your insurance costs.
State Farm offers a variety of discounts including multi-policy and safe driver discounts. Meanwhile, if you’re in the military or a good student, Geico might have some sweet deals for you. The key is to ask and explore!
Tips for Finding the Best Insurance Rates in NC
Are you overpaying for insurance in North Carolina? You could be missing out on major savings just by not knowing where to look.
Let’s dig into some smart strategies that can help you snag the best deals on insurance rates in the Tar Heel State.
Strategies for Negotiating Lower Insurance Rates
Insurance companies are like any other business. They want your money. BUT, here’s the deal: they also want to keep you as a customer. So, negotiating can work wonders.
- Step #1: Gather quotes from multiple providers. Competition can be your best friend.
- Step #2: Highlight your loyalty if you have been with the same provider for a long time. Use it as leverage.
- Step #3: Ask for discounts—whether it’s for bundling policies or having a good driving record. You’d be surprised what you might qualify for!
Pro Tip: Always be polite but firm. The person on the other end wants to help you save so you stick around.
Methods to Improve Your Insurance Score
Did you know your insurance score can make or break your rate? It’s like a credit score but for insurance.
- Pay your bills on time. Late payments can ding your score.
- Reduce outstanding debt. Lower debt equals lower risk in the eyes of insurers.
- Regularly check your insurance score and dispute any inaccuracies.
Pro Tip: Consider taking a defensive driving course. It can boost your score and reduce rates!
Checklist for Reviewing an Insurance Policy Prior to Purchase
Before you sign on the dotted line, make sure you’re getting what you need. Here’s a checklist to guide you:
- Coverage Details: Ensure the policy covers all your needs.
- Deductibles: Know what you’ll have to pay out of pocket.
- Exclusions: Be clear about what’s not covered to avoid surprises.
- Claim Process: Understand how to file a claim and get it processed quickly.
Pro Tip: Don’t just look at the price. Consider the value and coverage you’re getting for your money.
Steps to Take When Switching Insurance Providers
Thinking about switching but worried about the hassle? Here’s how to make the transition smooth:
- Review your current policy and note down what you like and don’t like.
- Get quotes from new providers and compare them to your current policy.
- Overlap your policies for a few days to avoid coverage gaps.
- Formally cancel your old policy once the new one is active. Avoid any lapses in coverage.
Pro Tip: Ask your new provider if they handle cancellations on your behalf. Some do!
Common Mistakes to Avoid When Selecting Insurance
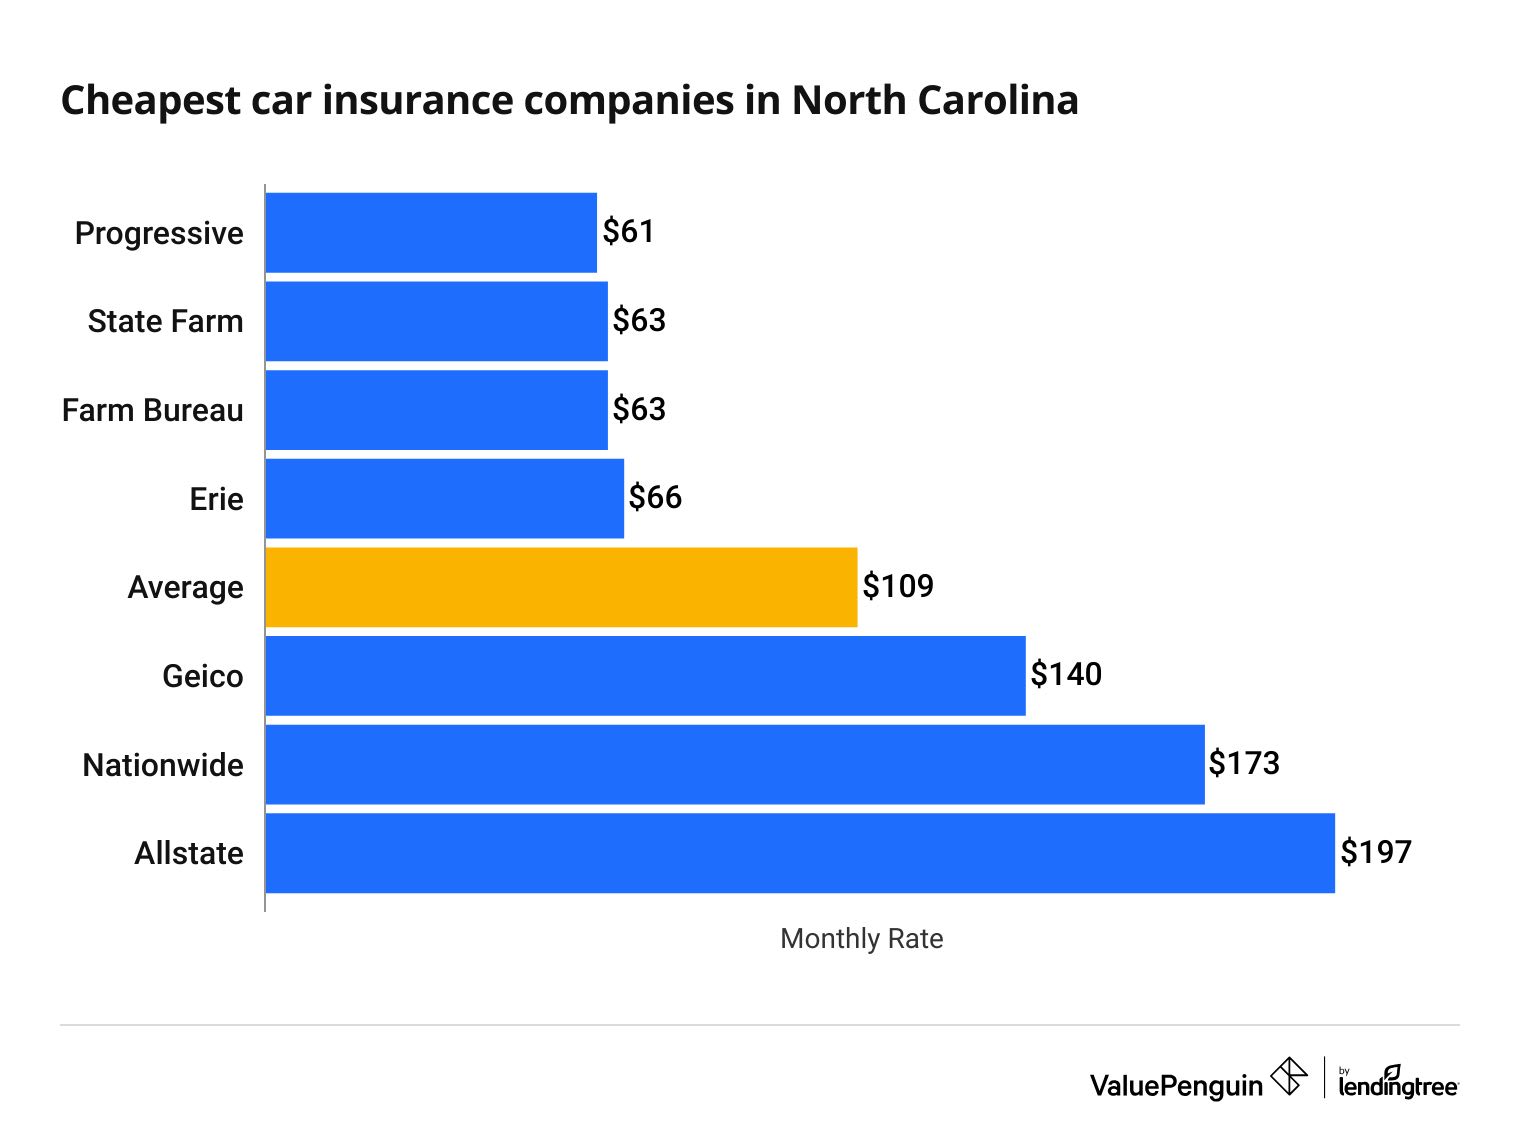
Ever felt like you’re paying too much for insurance, or worse, not enough? You’re not alone. Most people stumble into the same traps when choosing their policies.
Understanding these pitfalls can save you a lot of money and heartache. Let’s dive into some of the most common mistakes you can avoid.
Over-Insuring and Under-Insuring: The Balancing Act
It’s tempting to go for the lowest premium or the highest coverage out there. BUT here’s the deal: both can leave you in financial ruin. Under-insuring means you might face hefty out-of-pocket expenses during a claim. On the flip side, over-insuring is like throwing money away on coverage you’ll never use.
Pro Tip: Regularly review your coverage levels to match your current life situation.
Misleading Policy Terms: Read Between the Lines
Insurance jargon can be confusing. Some terms might sound like a good deal when they’re not. For example, a “limited coverage” term could mean your policy only kicks in under specific conditions. Skipping the fine print might leave you with a policy that doesn’t cover what you thought it would.
Always ask for clarification on terms that seem too good to be true.
Importance of Regularly Updating Coverage
Your life isn’t static, and neither should your insurance be. Major life events like buying a house, having a baby, or retiring can drastically change your insurance needs. Failing to update your policy can lead to gaping holes in coverage or paying for unnecessary extras.
Make it a habit to review your insurance at least once a year or whenever a significant life event occurs.
Future Trends in Insurance Rates in NC
Buckle up because the insurance industry in North Carolina is about to be turned on its head. As climate change, tech advancements, and new laws sweep through the state, you can expect insurance rates to experience some significant shifts.
Here’s the deal: Insurance companies are on high alert. They’re adjusting their strategies to keep up with the times, and that means you could see fluctuations in your premiums.
Impact of Climate Change on Insurance Rates
Did you know that extreme weather events have increased by 83% over the last two decades? This has insurance providers scrambling to adjust their rates. Rising sea levels and more frequent storms mean higher risk, which often translates into higher premiums. If you live near the coast, expect these changes to hit you first.
Pro Tip: Consider investing in flood insurance now, as rates are likely to climb in the near future.
The Role of Technology in Shaping Insurance
Self-driving cars, IoT devices, and AI are set to transform the insurance landscape in NC. Insurers are increasingly using telematics to track driving behavior and offer more personalized rates. This tech-driven approach might offer discounts but also raises privacy concerns.
Pro Tip: If you’re a safe driver, look into telematics programs—they could save you a bundle!
Legislative Changes and Their Impact
New laws in NC could dramatically alter how insurance is priced. Recent legislation aimed at improving transparency and consumer rights is pushing insurers to reassess their pricing models. You might find that your coverage options expand as a result, but keep an eye on the fine print for any hidden costs.
Emerging Insurance Products and Services
As customer demands evolve, so does the range of insurance products. From cyber insurance to policies covering climate-induced damages, new products are arriving on the scene. Insurers are keen to cater to niche markets, and you might find some innovative solutions to meet your specific needs.
Shifting Customer Preferences
The modern consumer is more informed and expects customized insurance solutions. This shift is driving insurers to offer flexible plans and digital services. If convenience and personalization are what you crave, the market is moving in your direction.
Pro Tip: Always compare digital-first insurance providers—they often offer better rates and more flexibility.
Final Summary
As you embark on your journey to secure the best insurance rates in NC, remember: knowledge is your most significant asset. By understanding the factors at play and staying informed about emerging trends, you’re well-positioned to make savvy insurance choices. Keep this guide handy, and let it be your compass as you navigate the dynamic landscape of North Carolina insurance.
FAQ
What factors affect insurance rates in North Carolina?
Several factors influence insurance rates in NC, including your driving record, credit score, age, and the type of vehicle you drive.
How can I improve my insurance score?
Improving your insurance score involves maintaining a good credit score, having a clean driving record, and minimizing insurance claims.
What types of insurance are available in NC?
In NC, you can find various insurance types, including auto, home, health, and life insurance, each offering different levels of coverage.
Why should I consider bundling my insurance policies?
Bundling policies, such as auto and home insurance, can lead to significant discounts and simplified management of your coverage.
What should I look for when comparing insurance providers in NC?
Compare customer service ratings, financial stability, claims processes, and available discounts when choosing an insurance provider in NC.
